
September 1, 2026 | 24 mins 22 secs
For the latest standardized performance and holdings of Sprott Precious Metals ETFs, please visit the individual website pages: GBUG, SGDM and SGDJ. Past performance is no guarantee of future results.
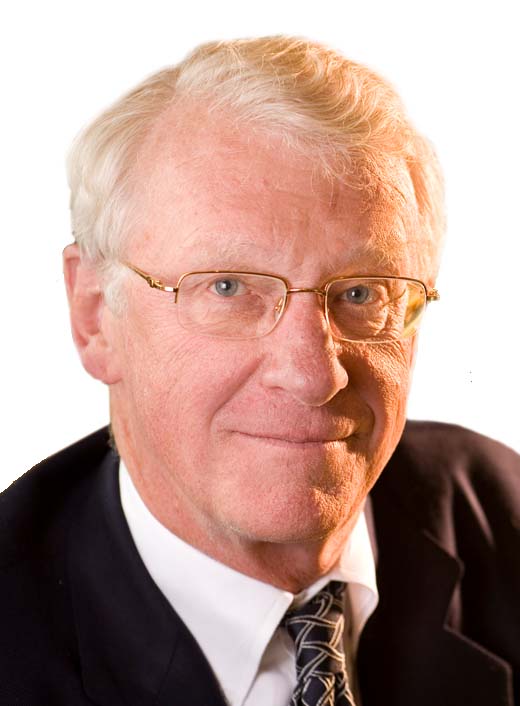
Gold stocks may be entering a new phase of leadership as stronger balance sheets, growing free cash flow and historically low valuations strengthen the investment case. At the 2026 Precious Metals Summit in Beaver Creek, John Hathaway, Managing Partner at Sprott Asset Management, joins Kitco Mining's Paul Harris to discuss why he views gold as an "all-weather strategy" and why the outlook for gold equities may be improving. Hathaway explains how stronger capital discipline, potential M&A and miners' operating leverage could position select gold equities to outperform—even if gold prices do not move higher.
Video Transcript
Paul Harris: Hello, and welcome to Kitco Mining with me, Paul Harris, here at the 2026 Precious Metals Summit in Beaver Creek, Colorado. We're kicking off day two with one of the legends in the gold investment space. It's a great pleasure to be joined by John Hathaway, Managing Partner at Sprott Asset Management. John, welcome back to Kitco.
John Hathaway: Thank you, Paul.
Paul Harris: John, I want to start by taking advantage of this opportunity. A lot is going on today that I wanted to get into with you, but perhaps I should frame it in a broader context. Maybe we can go back to the early days of your career when you started as an equity analyst in the 1970s. What was it that drew you to investing? When did gold become a serious part of your thinking and what you do?
John Hathaway: I had a whole other career before I got involved in gold. I followed paper and forest products stocks, resource stocks in general. I did that for several years, probably a decade and a half. Then I went to the buy side at a value firm, David J. Greene, which no longer exists. In fact, every firm I worked with no longer exists.
Paul Harris: Is that the kiss of death, or was it so much success that people bought you?
John Hathaway: I don't think it was me. I think it was just the evolution of the business. Then in 1998, I joined a former colleague of mine from David J. Greene at Tocqueville Asset Management. We were a contrarian value firm, which was what I had become at that stage. We decided to launch a gold fund. We did that in June 1998 with $10 million of our own and our clients’ money. It grew to $3 billion over the next 15 years or so. That was a big success, but it basically got me full-time, 100% into the space that we're in now.
Paul Harris: Tocqueville was eventually acquired by Sprott in 2020, if I'm not mistaken.
John Hathaway: My business at Tocqueville was acquired by Sprott in 2020.
Paul Harris: How has being at Sprott changed what you can do as an investor? Is it just, "John, you're doing great, carry on," or "We'd like you to do something perhaps a little bit different?"
John Hathaway: No. It was the idea that Sprott was looking for an active manager and team to fill out their suite of what they do. When I joined Sprott in 2020, I think the AUM was less than $15 billion, and today it's almost $60 billion.
Paul Harris: That's quite a bit of growth. Now, you've invested through cycles of inflation, deflation, financial crises, technology bubbles and several commodity cycles, of course. Which period or what situation has done the most to shape your approach to investing in the sector?
John Hathaway: I would say all of the above. Frankly, to me, gold is an all-weather strategy not recognized as such. It's usually thought of as a doomsday solution to all the worries out there on the front pages, and maybe ones that have yet to pop up. But gold is a diversifier, and that's been academically justified and proven. I like to say that gold has outperformed the S&P 500 since 2000, which was the dawn of radical monetary experimentation by the central banks. It's not by a huge amount, but it has not only kept pace with the S&P 500 but also beaten it, with dividends reinvested.
Paul Harris: Over the course of your career, I think it would be fair to say that more information has become available, more tools have become available. Has the mining industry, therefore, become easier to analyze and invest in over the years, or have other things continued to make it complicated and challenging?
John Hathaway: It's always challenging. But I think it's a better industry than it was at the last peak in the gold price, in 2011. I remember it well. I think the industry has come a long way in capital allocation, general financial management and all of that. Obviously, today it's way more profitable than it's been at any time in my history since '98. It's changed in that way, but it's always complicated. If you look at a bottom-up analysis, every asset and jurisdiction differs. We dig into all of that.
Paul Harris: It's very interesting and pertinent that you talk about how the financial management of the gold miners has improved. Do you think they've completed that task, or is there still more for them to do?
John Hathaway: No, I think it's ongoing. One bee in my bonnet is that I think that the way they present their story could be vastly improved. I've seen 25 different presentations in the last couple of days. I'll see a few more today. They need to do a better job of laying out the investment thesis. Why should we, or anyone, invest in this particular stock? That should be on page one. You don't see that.
Paul Harris: John, you're preaching to the choir here. This is a real bee in my bonnet as well. I watch Shark Tank a lot. What do the sharks say to everyone? What's your business plan? Give me three things you're going to do. Nobody has that in their presentation.
John Hathaway: I'm not sure why it is that way, but it's an easy fix. It hasn't really been articulated. I think Ronnie Stöferle brought it up the other day, and he makes a great point that this industry could be way better at attracting generalists. Generalists are not interested in drill holes. They're interested in financial management, cash generation, growth (if any), and any problems. There's always something within any individual company that's particular to say, "Why is it going to go from A to B?"
Paul Harris: Absolutely. Investors want to hear a concept. They want to know how you will increase value, how long it will take, and how much it will cost. It doesn't need to be more complicated.
John Hathaway: It's quite simple. But they make it complicated. That could be one reason generalists have generally avoided the sector. It's so much easier for a generalist to invest in the metal. Frankly, the returns over a long period of time have not been that different. I think that's going to change. But so far, it's been much easier to get somebody to understand the thesis for investing in gold, the protection and diversification it offers. Then you don't have to do any forensic work on the underlying assets. The reason you would invest in a gold stock, in my mind, and it's starting to play out, is the torque that you get relative to directional changes in the gold price.
Paul Harris: I'd like to touch on another point that Ronnie talks about quite a lot, and that is the fact that most gold producers do not hold any bullion on their balance sheet. He wrote about this earlier this year. He presented quite a compelling argument, from protecting the assets, for if you really think the gold price is going to go up, you can benefit from that appreciation. Why don't companies do it?
John Hathaway: I think what's missing is that in the last 30 years or so, you don't see very many C-suites that champion the product that they produce. I'm not saying that a mining engineer should be conversant with all the mining issues, but there should at least be some sense that gold is a form of money. It's scarce. It's hard to get. They don't have to be chapter and verse on all the macro arguments, but you need to see more of an awareness of what they're doing and producing, which is very different than everyday industrial companies. Should they stockpile gold on the balance sheet? Yes, but you don't want to bet the ranch on that. They have to generate cash, which is what they do by selling the metal. At a time like this, when they're flush, why wouldn't you have some of your treasury invested in the metal?
Paul Harris: Absolutely. Going back to your earlier points about improved financial management, it would seem remiss of the management of the larger gold producers who have perhaps had more than a billion dollars in cash on their balance sheets for five years. Over five years, the purchasing power of that cash has diminished considerably. That would seem to be perhaps irresponsible.
John Hathaway: I wouldn't quite go that far. But I do think the point isn't lost. Having too much cash is not necessary. That's what you would call a lazy balance sheet. It should be deployed in share buybacks, returning it to shareholders through higher dividends, maybe judicious acquisitions, and bullion. But I think, again, it's all case-specific. Some of these companies are investing in growth, so they don't have free cash, and you can't blame them for not having physical metal. But the big guys should make a statement.
Paul Harris: I imagine this is going to become more of a challenge for them if high metals prices persist because they are making very good margins. They are increasing their returns to shareholders through buybacks and increasing dividends, but they're still perhaps having lazy balance sheets with too much cash just sitting there. Maybe there's some scarring from the down cycle. They feel they need that added cushion.
John Hathaway: I think there's a memory of the lean times, early post-2011 period, perhaps through the mid- to late 2010s. It was like a nuclear winter for the industry. But by and large, there's institutional memory of that, and from what I've seen over the last decade, there's been a huge amount of change at the top in the industry, and for the better, I would say.
Paul Harris: With the bigger producers being flush with cash, they're exploiting resources that are declining and degrading. There doesn't seem to be perhaps an urgency to replenish their pipelines by buying other companies, which is a legitimate use of the money they're generating. Why do you think that is? At this point in the cycle, would you expect to see more buying of other companies, smaller companies or development assets?
John Hathaway: I think that's just around the corner. We've seen some M&A, bolt-on acquisitions and larger mergers. The cash is burning a hole in their pockets. The question is what to do with it? We've talked about share buybacks, dividend increases, or maybe stockpiling bullion. Of course, the valuation of everything in the space has gone up. But at the end of the day, when you look at the margins companies are generating and the valuations in the space, which are ridiculously low, especially if you have a positive view of the gold price, there's work to be done on the M&A side.
Paul Harris: Given your viewpoint that the gold and silver equities are still historically inexpensive, where do you see the best opportunities for investment at the moment? When you put your fund management hat on, where do you see the best risk-reward?
John Hathaway: Generally speaking, the day has come for the gold stocks to start to perform. That's without any increase in the gold price. If the gold price goes up further, I think there's a lot of potential. You can almost throw darts. We would never do that, but you almost could. First, you want a good mix of solid big-cap producers; then look for growth stories and takeout candidates. We do this every day. There's a lot to be done.
Paul Harris: You mentioned the big producers, the medium producers and the developers. It sounds like there's a lot of opportunity in those, so perhaps you don't need to take on the risk of the explorers at the moment.
John Hathaway: No. You don't. But when you think about it, pre-2011, there was huge money made in the small-cap names. Every half hour, I have a new story. Or not a new story, but we obviously talk to companies we own. First of all, there are many bright people in the space and many ambitious younger teams building companies. The question we always ask a developer is: When will the project begin generating cash? For some of them, you're going to have to wait five or six years. Maybe that's too long a wait for the way we do things. But if it's in a year or two years, that's exciting, especially if it's not properly priced.
Paul Harris: Absolutely. For the producers, the average all-in sustaining cost at the moment is around US$1,900 per ounce, which means they're getting an all-in sustaining cost margin of $2,000-$2,400 per ounce. That's obviously very strong and explains why they're having very strong free cash flows and very strong record cash positions. How sustainable do you think these margins are, with all-in sustaining cost margins of 60% to 70%? Or should investors expect that, sooner or later, labor, energy, and equipment costs, as well as government take, will eat into those margins?
John Hathaway: I can never understand the 2% number that the Fed talks about, which they've never done, and we've never had in years and years. I think the inflation rate, especially for CapEx, doesn't even account for labor, which is a huge issue, too. But it's more like 10%. To me, that's a better read on the inflation rate than the ridiculous numbers the Fed and people who follow it parse every day on TV. I think the real inflation number, based on what we see in the real world at mining companies, is not 2%. It's probably 8%-9% and could be as high as 10%.
Paul Harris: The gold price has been accelerating more than the cost.
John Hathaway: Yes. Margins have expanded. But if we mark time here for two or three years in the mid-four thousands for the gold price, I think you will see margins constrained.
Paul Harris: The gold price hit an all-time high of over US$5,000 per ounce earlier this year. It's pulled back down to $4,000. We're currently at $4,200 or $4,300. We seem to be in a bit of a consolidation phase. Speaking with Ronnie Stöferle yesterday, he said the thesis still stands: gold will eventually move up towards $8,900.
John Hathaway: That's his number.
Paul Harris: That's his number in, I think he said, within five years.
John Hathaway: It's a very logical case.
Paul Harris: For you, what would indicate that the gold cycle is perhaps becoming speculative and approaching its later stages?
John Hathaway: Earlier this year, we saw a parabolic rise in the price of gold, silver and stocks. I've been in markets for over 50 years. That was an important top. I would be very happy if we got through the rest of this year where we are. I think shares are up roughly 11% year-to-date, using GDX as a proxy. The gold price is flat. I'd be delighted if that were the year-end number, because I think you need to consolidate and burn off the excessive sentiment we saw at the end of January. Then you're right, it's a consolidation phase. It's good. It needs to happen. Sentiment has dropped quite a bit. I think we're in a way better place than we were. But I think that was an intermediate top. I agree with Ronnie, it could double from here. I think it could be in 5 digits.
Paul Harris: We've spoken about a lot of things, but one of the key things people in the gold sector often ask is, "When are the generalists going to show up?" The S&P 500 and tech stocks have been very strong. When are investors going to start cycling into the resource stocks? We're seeing gold producers with record margins, record cash flow, really strengthening their businesses. Is that what it's going to take for the generalists to start taking positions again in the mining space?
John Hathaway: I think that's part of it. I think one thing that really has to happen is that the generalist investor has to lose confidence in his current positioning, and that would be bonds. We're seeing every day that bonds are just a horror story. We need to see some migration out of bonds. I think if we see a drawdown as we saw in 2000, the dot-com bust, and God forbid, we have another GFC as we had in '07, '08, those would be the events that I would say would make people rethink their positioning. I think that, in the process, they will discover gold as a safe haven and explore ways to enhance their exposure. We're beginning to see it. But look at GDX: flows are pathetic. Then look at GLD. Its price is way up, but its gold holdings are lower than they were five years ago. Holdings across the various iterations of GLD and other gold-backed ETFs are also lower. That's incredible to me. If you do a census of exposure to just gold, the metal, it's like 1% or 2%. It's hard to get good numbers, but it's not 10%. I think if people take someone like Mike Wilson of Morgan Stanley at his word, 20% in gold instead of 40% in bonds, 20% bonds, 20% in gold, you could easily get to a five-digit number in the gold price.
Paul Harris: Let's end, John, by looking forward and looking backward at the same time. People learn by looking backward at what happened, analyzing it, drawing conclusions and learning from their mistakes. When investors look back in five years to the present period, what do you think will seem obvious in hindsight?
John Hathaway: I think they'll see that the S&P 500 has been driven by a small number of stocks, high concentration in the AI investment thesis, and all the iterations of that. That was way overdone. To me, it's obvious today. But I think in five years, I would be astonished if there wasn't a big setback in that whole thesis, and we could talk forever about why that would be the case.
Paul Harris: That would seem to be perhaps an echo of the dot-com boom.
John Hathaway: Then that's an echo of the dot-com boom. I also think that the fiscal issues that are becoming increasingly obvious and the reason why bonds are having such a hard time, I think people will say, "I saw that coming, but why didn't I do anything about it?" But I think those are the two main things I would mention. Private equity is another, and you could point to several other areas as well. The geopolitical situation is far more troubling today than it was five years ago. Yet, most investors, in my mind, are whistling past the graveyard there, and they say, "Well, they're going to fix it all. The Iranians will come to their senses." To me, the toothpaste is out of the tube. To me, that has a life of its own, which is scary, but I think the markets are not positioned for what I consider reasonably justifiable outcomes there: a prolonged mess.
Paul Harris: Holding on until you can't hold on any longer. This has been fantastic. I appreciate you spending some time with us today. John Hathaway, thank you very much for joining me.
John Hathaway: Thank you, Paul.
Investment Risks and Important Disclosure
Relative to other sectors, precious metals and natural resources investments have higher headline risk and are more sensitive to changes in economic data, political or regulatory events, and underlying commodity price fluctuations. Risks related to extraction, storage and liquidity should also be considered.
Gold and precious metals are referred to with terms of art like "store of value," "safe haven" and "safe asset." These terms should not be construed to guarantee any form of investment safety. While “safe” assets like gold, Treasuries, money market funds and cash generally do not carry a high risk of loss relative to other asset classes, any asset may lose value, which may involve the complete loss of invested principal.
Past performance is no guarantee of future results. You cannot invest directly in an index. Investments, commentary and opinions are unique and may not be reflective of any other Sprott entity or affiliate. Forward-looking language should not be construed as predictive. While third-party sources are believed to be reliable, Sprott makes no guarantee as to their accuracy or timeliness. This information does not constitute an offer or solicitation and may not be relied upon or considered to be the rendering of tax, legal, accounting or professional advice.
Important Disclosures
An investor should consider the investment objectives, risks, charges and expenses of each fund carefully before investing. To obtain a fund’s Prospectus, which contains this and other information, contact your financial professional, call 1.888.622.1813 or visit SprottETFs.com. Read the Prospectus carefully before investing.
Exchange Traded Funds (ETFs) are considered to have continuous liquidity because they allow for an individual to trade throughout the day, which may indicate higher transaction costs and result in higher taxes when fund shares are held in a taxable account.
Diversification does not protect against loss. The funds are non-diversified and can invest a greater portion of assets in securities of individual issuers, particularly those in the natural resources and/or precious metals industry, which may experience greater price volatility. Relative to other sectors, natural resources and precious metals investments have higher headline risk and are more sensitive to changes in economic data, political or regulatory events, and underlying commodity price fluctuations. Risks related to extraction, storage and liquidity should also be considered.
Gold and precious metals are referred to with terms of art like "store of value," "safe haven" and "safe asset." These terms should not be construed to guarantee any form of investment safety. While “safe” assets like gold, Treasuries, money market funds and cash generally do not carry a high risk of loss relative to other asset classes, any asset may lose value, which may involve the complete loss of invested principal.
Shares are not individually redeemable. Investors buy and sell shares of the funds on a secondary market. Only “authorized participants” may trade directly with the fund, typically in blocks of 10,000 shares.
The Sprott Rare Earths Ex-China ETF is new and has limited operating history.
Sprott Asset Management USA, Inc. is the Investment Adviser to the Sprott ETFs. ALPS Distributors, Inc. is the Distributor for the Sprott ETFs and is a registered broker-dealer and FINRA Member. ALPS Distributors, Inc. is not affiliated with Sprott Asset Management USA, Inc.