
November 12, 2026 | (15 mins 12 secs)
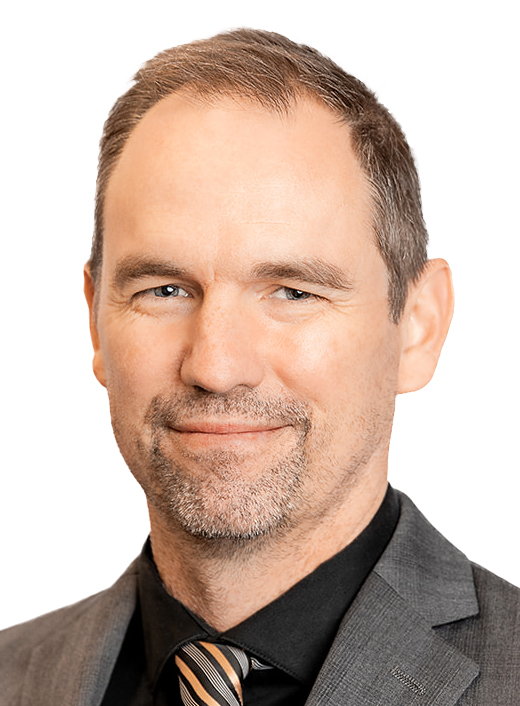
In this episode of Metals in Motion, Thalia Hayden @etfguide chats with Justin Tolman, BSc (Hons), MBA, Senior Portfolio Manager and Economic Geologist at Sprott Asset Management, about the gold market, and the structural, macroeconomic trends driving precious metals moving forward.
For the latest standardized performance and holdings of Sprott Active Metals and Miners ETF, please visit GBUG. Past performance is no guarantee of future results.
Video Transcript
Thalia Hayden: You're watching Metals in Motion. I'm Thalia Hayden with ETFguide. Joining us today is Senior Portfolio Manager and Economic Geologist at Sprott Asset Management, Justin Tolman. Welcome, Justin. Great to see you again.
Justin Tolman: You too, Thalia. Thanks for having me back.
Thalia Hayden: What's the current macroeconomic backdrop behind gold and silver bullion today?
Justin Tolman: I think the important thing in that question is the word today. The macroeconomic drivers that have caused the gold price to double since the start of 2024 remain in place and active. These drivers include rising global debt, currency debasement and the rise of real assets.
But here and now, the immediate backdrop is a tug-of-war between tight financial conditions and strong underlying demand. Ten-year Treasury yields are sitting up around 5%, and the U.S. dollar’s as high as it's been since early 2025. And that raises the opportunity cost of owning metals that don't pay any income. That's a cyclical headwind, and it's something that's putting pressure on metal prices today. But on the other side, the dip is being bought. Gold ETFs took in $31 billion in Q3. That's a record, and I was really pleased.
September was a tough month. Gold fell 8% and change. But that was driven by selling from futures positioning. The ETFs took in $10 billion USD. Holdings exceeded 4,200 tonnes. We saw such strong buying in Indian gold ETFs that fund houses had to curb new subscriptions. What is new today is that you're seeing investors step in on this dip, buying at the top of the floor that’s been set over the last few years by central banks.
You mentioned silver as well. Silver shares the same monetary backdrop. But it's a smaller market, and it's more volatile. It kind of behaves like gold with more torque. But the structural case remains very strongly intact underneath the cyclical correction.
Thalia Hayden: Justin, you mentioned Treasury yields. They've risen sharply this year, and fiscal strain for governments everywhere is intensifying. How much debt is too much, and is gold still the go-to asset for neutralizing credit risk?
Justin Tolman: How much debt is too much is tricky. I don't think there's a magic debt-to-GDP number. Debt can become too much when markets start to doubt that governments can service it without imposing a cost elsewhere. That's not really a math problem for analysis. It's a credibility or flexibility problem. If yields rise too much, interest expense consumes a larger share of government revenue. If you push yields down too far, you risk inflation or currency weakness. But I think what matters more is why the yields are going up. What's the source? If it's driven by strong growth, as I said, that can be a headwind for hard assets without yield.
But if yields are rising because of fiscal supply, rising term premiums or fading confidence in the sovereign’s ability, that reinforces the value of an asset like gold. Gold’s a hedge for that second case in yields because it's nobody's liability. It has no issuer. It has no maturity date. It doesn't depend on a promise from someone's balance sheet. It doesn't have any credibility to lose. Which isn't to say that gold replaces Treasuries. To answer the second part of your question: Treasuries remain a liquid asset, but gold helps protect against dilution. It provides diversification. In the worst case, it protects against confiscation. And you're seeing reserve managers acting on this.
I mentioned central banks a second ago. They've been buying about 1,000 tons of gold over the last four years, accelerating their purchases. The World Gold Council recently conducted a survey: about 90% of respondents expect central bank gold reserves to rise next year. The people who make a living holding sovereign debt are diversifying away from it.
Thalia Hayden: Sprott’s research says gold miners have entered a new era of stronger balance sheets. Has the market fully priced in that shift, or are valuations still lagging the fundamentals?
Justin Tolman: I talked about this recently, and I think this is an interesting point. No is the short answer. I don't think the market has fully recognized that earnings are improving. Or maybe it recognizes it, but it hasn't fully accepted that the improvement is durable. Gold is up, let’s call it 100%, since the start of 2024. And the gold equities did what they're supposed to do; they provided leverage, and they've gone up 200% in that time.
But if you look at 2027 earnings for the miners, they’ve increased to 3.3 times their previous level. Earnings expectations have risen faster than share prices. And this compresses the implied earnings multiple by about 30%. They've gotten cheaper on a multiple basis. This isn't just a question of whether the market has priced in stronger balance sheets. What I don't think the market has fully priced in is better management. And that hesitation is understandable.
In past cycles, generalists have come in just to watch this sector destroy capital at the top. But that behavior has changed. Ten years of a bear market will build up some scar tissue and some discipline. And the business was profitable before the prices rose. But now you're seeing the intersection where stronger discipline meets higher prices. And it's really strong. As an industry, we’re net cash right now; we're buying back stock at a level I've never seen before. We're paying dividends. And this is after reinvesting in the business. When we compare this to the broader market, I've got the gold mining index trading at about 6x EV-to-EBITDA. Compare that to the S&P 500, which is 13 or 14 times. Many generalists will probably want to see two or three years of evidence before treating it as durable. That's fair. But that delay is the opportunity. And that's where Sprott, as a dedicated natural resource specialist, sees the benefits of being early in the cycle.
Thalia Hayden: Let's talk about silver now, Justin. Compare silver miners versus physical silver based on today's market dynamics. Which one holds the advantage?
Justin Tolman: I don't know that advantage is the right way to frame it. Physical silver and silver miners kind of express the same view, but with different risk profiles. It comes down to your risk tolerance. Physical silver is clean. You own the price. You take on no operating, financing or political risk. Miners will give you leverage. You will own the margin. You get the price less a fixed cost base or a largely fixed cost base, which gives them torque. And as a result, the miners will carry risks that bullion doesn't.
I mentioned earlier that silver is “higher-beta gold.” The silver miners are higher-beta silver. The trouble with the silver mining equities is that it's not a homogeneous environment. Some companies have very strong balance sheets. They've got great mines with long reserve lives, well-known and understood cost structures and good new discoveries. Other “silver miners,” in inverted commas, are base metal businesses masquerading as silver or gold businesses masquerading as silver. Only about a quarter of the silver mined comes from primary silver mines.
Some companies will need substantial new development capital, so I wouldn't buy the average silver miner just because I'm bullish on silver. The work is in finding the good ones out there. Bullion is how you own silver. The right miners are how you get paid for being right on the thesis.
Thalia Hayden: One more question before we let you go. How does active management in gold and silver miners potentially make a difference?
Justin Tolman: Now you're aware that you're asking an active manager whether active management makes a difference, right? I would say the mining industry is a powerful market for active management because the differences between companies are enormous. We've made slides in our decks showing the dispersion of returns from mining equities in any given year. And the average is super misleading. Around that average, you've got tremendous error bars. It's the same metal with radically different shareholder outcomes. And this is where management, active stock picking and active management can help or hurt. If you do a bad job, you'll be way over on the wrong side of your distribution. Whereas if you just own the index, you'll get the average.
If you do a good job, there's a small number of companies that add a disproportionate amount of value, and that shouldn't be a surprise. You see it in nature all the time. You see it in ore bodies. There's a handful of ore bodies that add most of the value. The active diligence we apply to stock selection goes far beyond just screening earnings multiples. We will look at the underlying geology, the mine plan, the metallurgy, the company's balance sheet, management's pedigree and an overlay for political risk. We’re not just trying to find the best ore bodies and the best businesses, but, in the same way, to avoid the other end of that spectrum. To build on what we said for silver, the metal price creates the opportunity. But the stock selection really determines how much of that opportunity comes back to the shareholder again. We do a lot of site visits, management outreach and screening. To bring it full circle, we're in the camp that believes an active investor can add value.
Thalia Hayden: We certainly learned a lot today. Thank you so much, Justin, for your time, and we appreciate your timely insights. Keep up the great work.
Justin Tolman: Thank you, Thalia. This is fun.
Thalia Hayden: It sure is. And from gold and silver miners to the critical materials powering the future, discover the full lineup at SprottETFs.com. I'm Thalia Hayden with ETFguide. Thanks for watching, and we'll see you next time.
Important Disclosures & Definitions
An investor should consider the investment objectives, risks, charges, and expenses of each fund carefully before investing. To obtain a fund’s Prospectus, which contains this and other information, contact your financial professional, call 1.888.622.1813 or visit SprottETFs.com. Read the Prospectus carefully before investing.
Exchange Traded Funds (ETFs) are considered to have continuous liquidity because they allow for an individual to trade throughout the day, which may indicate higher transaction costs and result in higher taxes when fund shares are held in a taxable account.
The funds are non-diversified and can invest a greater portion of assets in securities of individual issuers, particularly those in the natural resources and/or precious metals industry, which may experience greater price volatility. Relative to other sectors, natural resources and precious metals investments have higher headline risk and are more sensitive to changes in economic data, political or regulatory events, and underlying commodity price fluctuations. Risks related to extraction, storage and liquidity should also be considered.
Shares are not individually redeemable. Investors buy and sell shares of the funds on a secondary market. Only “authorized participants” may trade directly with the funds, typically in blocks of 10,000 shares.
Sprott Asset Management USA, Inc. is the Investment Adviser to the Sprott ETFs. ALPS Distributors, Inc. is the Distributor for the Sprott ETFs and is a registered broker-dealer and FINRA Member. ALPS Distributors, Inc. is not affiliated with Sprott Asset Management USA, Inc.